
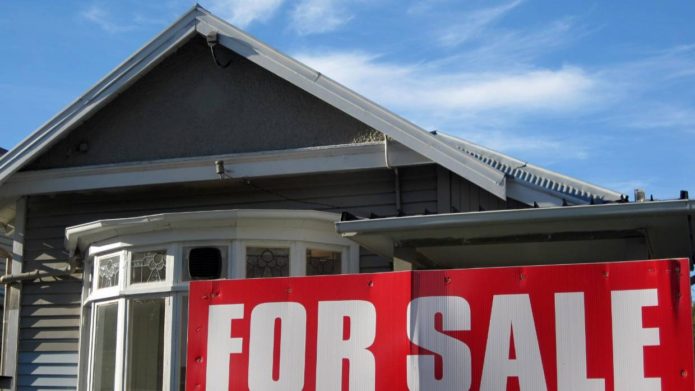

PHOTO: Nearly $2 billion – and vendors still pay for the advertising.
New Zealand homeowners are watching property values slide while the country’s real estate commission machine continues generating extraordinary revenue. Is it finally time to challenge the percentage-based commission model?
New Zealand’s housing market is weakening again.
Property values have fallen for six consecutive months. Buyers hold the negotiating power. Listings remain plentiful, sales activity is subdued and thousands of homeowners who purchased near the market peak are watching their equity disappear.
Yet one part of the property machine continues to generate astonishing amounts of money.
Real estate commissions.
Interest.co.nz estimates New Zealand’s real estate industry earned just under $2 billion in gross residential sales commissions during the 12 months to June 2026.
That was approximately 4.5% more than during the previous 12 months.
Read that again.
Nearly $2 billion in gross commissions—in a housing market repeatedly described as flat, fragile, subdued or falling.
The figure does not mean every real estate agency or salesperson is thriving. Gross commission is not profit, and the money must support salespeople, offices, administration, franchise fees, marketing, compliance and properties that never sell.
However, it exposes an increasingly uncomfortable imbalance.
Homeowners carry the financial risk.
Vendors absorb falling prices.
Sellers frequently pay the advertising costs.
But the traditional percentage-based commission model continues extracting tens of thousands of dollars from each successful sale.
Nearly $2 billion—and vendors still pay for the advertising
Interest.co.nz estimated the industry generated approximately $484 million in gross residential commission during the second quarter of 2026.
That was down 3.3% from the same quarter in 2025, reflecting deteriorating market conditions across much of the country.
However, the annual result remained extraordinary.
Gross residential commissions for the 12 months to June were just under $2 billion, up 4.5% from the previous year.
Earlier in 2026, the commission machine was running even faster.
Agencies reportedly generated approximately $474 million during the first quarter alone, the strongest first-quarter result since the 2021 property boom.
The estimated national average commission was slightly above $25,000 including GST, while the Auckland average was reportedly around $30,000.
Those figures generally excluded additional costs such as legal fees, home staging and auction expenses. Vendors may also pay separately for photography, video, floor plans, signage, print advertising and premium property-portal placement.
The result is a peculiar arrangement.
The homeowner supplies the million-dollar asset.
The homeowner accepts the risk that its value may fall.
The homeowner can spend thousands preparing and promoting it.
Then the homeowner hands over another $20,000, $30,000 or even $40,000 when it sells.
The housing recovery has disappeared
The size of the commission pool becomes even more confronting when placed beside the latest housing data.
Cotality’s September Home Value Index recorded a further 0.3% national decline—the sixth consecutive monthly fall.
Property values were 1.3% lower than a year earlier, while the national median value had slipped to approximately $797,078, below the previous cycle low recorded in June 2023.
As Property Noise reported in The Property Recovery Is Dead: NZ House Values Fall for Sixth Straight Month, Auckland fell another 0.5% during September and Wellington dropped 0.7%.
Lower Hutt recorded an especially sharp monthly decline of 0.9%.
Treasury has also dramatically reduced its outlook for the market. As Property Noise reported in The Housing Recovery Just Vanished: Treasury Slashes House-Price Forecast From 4% to Almost Zero, forecast house-price growth for 2027 has been cut to just 0.6%.
The national decline does not mean every homeowner has lost money. People who bought many years ago may still hold substantial equity, and some regional markets have performed better.
But owners who purchased near the 2021 peak face a profoundly different reality.
Some have seen hundreds of thousands of dollars erased from paper valuations. Others must sell into a market where buyers can negotiate aggressively, impose conditions or simply walk away.
The vendor may accept $50,000 less than expected.
The commission is still deducted.
Falling prices do not necessarily mean cheap commissions
Percentage commissions create a remarkable form of protection for the real estate industry.
When property values increase, commissions automatically rise—even if the work involved in selling the property remains broadly unchanged.
When values fall, commissions may decline slightly, but they remain substantial because New Zealand houses are still expensive in absolute terms.
A 2.5% fee on an $800,000 property is $20,000 before considering whether GST or other charges apply.
At $1.2 million, the same percentage produces $30,000.
At $1.6 million, it produces $40,000.
Does selling the $1.6 million property necessarily require twice as much work as selling the $800,000 property?
Sometimes a premium property requires specialist marketing, an extended campaign and complex negotiations.
Sometimes it does not.
Property Noise examined this issue in The $30,000+ Question: Are Real Estate Commissions Still Justified?.
Using an illustrative tiered structure of 3% on the first $400,000 and 2% on the balance, plus a $500 administration fee and GST, the commission on a $1.2 million sale could reach approximately $32,775.
That is before separate advertising and presentation expenses.
For many households, $32,775 represents years of savings.
Inside a property transaction, however, it can disappear as one line on the settlement statement.
The agent does not personally pocket the entire amount
Fairness requires an important distinction.
Gross commission revenue is not the same as agency profit or salesperson income.
The commission can be divided between the listing salesperson, another salesperson who introduces the buyer, the agency, the franchise group and referral partners.
From their share, agents may need to cover tax, vehicle expenses, photography contributions, personal marketing, database systems, licensing costs and unpaid time spent pursuing listings they never win.
Many salespeople earn considerably less than the public assumes. Some struggle to survive during weak markets, particularly when too many licensed agents are chasing too few completed sales.
Property Noise’s investigation, Too Many Agents, Not Enough Sales? The Numbers Behind NZ Real Estate’s Brutal 2026, found approximately 12,850 licensed salespeople competing as transaction volumes weakened.
For some agents, the downturn has become intensely personal. In “It’s Really, Really Tough”: NZ Real Estate Agents Turning to Side Hustles as Sales Dry Up, agents described supplementing their commission income through secondary jobs and selling personal possessions.
Good agents also provide genuine value.
A skilled salesperson can identify the correct market strategy, create competition between buyers, uncover problems before they derail the transaction and negotiate a result substantially better than the vendor might have achieved alone.
Commission-only work can produce an extraordinary income for top performers—but nothing for agents who fail to complete a sale. Property Noise examined that reality in The $0 Paycheque: How NZ Real Estate Agents Can Work All Week and Legally Earn Nothing.
But none of that answers the central question:
Why should the price of the service be tied so heavily to the value of the homeowner’s asset?
Who created the property’s value?
An agent may work extremely hard to sell a home.
But the agent did not buy the land, service the mortgage, renovate the kitchen, replace the roof, maintain the garden or absorb years of rates and insurance increases.
The homeowner carried those costs.
Nor did the agent create the broader rise in land values caused by population growth, planning restrictions, inflation, infrastructure or housing scarcity.
Yet when those factors push a property’s value from $800,000 to $1.2 million, the percentage commission can increase by thousands.
The agent benefits from appreciation they did not create.
The vendor pays more for what may be a very similar service.
Now the market has turned.
Some homeowners are losing the gains they once held, but the industry’s commission structure remains anchored to historically high nominal property values.
That deserves scrutiny.
Does percentage commission really motivate a better result?
The traditional industry argument is that percentage commission aligns the interests of agent and vendor.
The higher the sale price, the more both parties receive.
The theory sounds persuasive. The mathematics can be less impressive.
If an agent earns a gross commission of 2.5%, securing another $20,000 for the vendor generates only another $500 in gross commission.
That $500 may then be divided between the salesperson and agency.
The vendor receives the overwhelming majority of the additional price, as they should.
But it also means the agent may gain relatively little by extending the campaign, risking the existing buyer or spending another week negotiating for the final $20,000.
This does not mean agents deliberately undersell properties.
It means percentage commission does not create the perfectly aligned incentives the industry often claims.
A hybrid model could provide stronger alignment: a reasonable fixed fee for completing the work, combined with a meaningful performance payment only on the amount achieved above an agreed benchmark.
The vendor pays whether the market is fair or not
A falling market puts vendors under pressure from every direction.
Their property may be worth less than expected.
Their mortgage may remain high.
Council rates and insurance premiums continue rising.
A new purchase may already be conditional on completing the existing sale.
If buyers know the vendor is under pressure, offers can become increasingly aggressive.
The vendor may eventually accept a price well below their original expectation.
The real estate commission is then calculated against the completed sale and deducted from the vendor’s remaining equity.
That is the harshest feature of the model.
The agent provides a service and deserves to be paid.
But the homeowner carries almost all the capital risk.
As explored in The Ultimate Property Crash? New Zealand’s Housing Market Is Falling Before It Ever Recovered, New Zealand’s market may be entering another downturn before the previous recovery properly arrived.
If sales weaken further, agencies will certainly feel the pain through lower transaction volumes.
But each homeowner who does sell may still surrender a five-figure commission at the precise moment their equity is already being squeezed.
Is competition delivering better value?
The commission debate also raises a broader competition question.
Property Noise has previously asked whether New Zealand has too many real estate agencies competing for a limited pool of listings, while large networks use their scale, databases and marketing power to defend market share.
In theory, more agents and more agencies should create stronger competition and lower selling costs.
But has that happened?
Or does competition mainly encourage agents to offer larger marketing campaigns, discounted advertising, ambitious appraisals and increasingly polished personal brands while the underlying percentage commission survives?
Auckland provides the clearest example of a market where major brands compete aggressively for dominance.
Property Noise’s analysis, The Auckland Agency War: Who Is Really the Number One Real Estate Agency in Auckland?, found Barfoot & Thompson retained the strongest evidence-backed claim to market leadership based on sales volume and branch reach.
Scale can generate genuine efficiencies.
But consumers are entitled to ask whether those efficiencies are being reflected in lower fees—or simply strengthening agency margins and market power.
Is the traditional model finally ready for disruption?
New Zealand vendors should have genuine alternatives.
These could include:
- A transparent fixed fee
- A lower base fee with a performance incentive
- An hourly professional-services model
- Tiered service packages
- Marketing included within the commission
- A capped commission for higher-value properties
- A success fee applying only above an agreed reserve or valuation
- A full written breakdown showing where the commission goes
The objective should not be to drive professional fees so low that competent agents leave the industry.
It should be to create a direct and defensible relationship between the work performed, the value delivered and the amount charged.
At present, that relationship is often unclear.
Two neighbouring properties may require similar photography, online advertising, open homes and negotiations.
Yet if one is worth substantially more, its owner can pay thousands more in commission.
That may be traditional.
It does not automatically make it fair.
Five questions every NZ vendor should ask
Before signing an agency agreement, homeowners should ask:
- What is the total commission, including GST, at several possible sale prices?
- Which marketing services are included—and which will cost extra?
- Is the commission negotiable?
- Will the agency offer a fixed-fee or performance-based alternative?
- What specific work or result justifies the amount being charged?
Vendors should also ask what happens if they withdraw the property, sell privately, change agencies or receive an offer from someone previously introduced by the agent.
The agreement matters.
A friendly appraisal meeting can end with the homeowner signing a contract carrying tens of thousands of dollars in potential costs.
The Property Noise view
New Zealand’s real estate industry is not doing anything unlawful by charging percentage-based commission.
Agents deserve payment for professional work, and exceptional agents can create results worth considerably more than their fee.
But a system that generated nearly $2 billion in annual gross commission while homeowners endured falling values demands serious examination.
The national average commission is now around $25,000 including GST.
In Auckland, it is reportedly around $30,000.
Marketing and other selling expenses can sit on top.
Meanwhile, property values have fallen for six consecutive months, buyers hold the power and heavily leveraged owners continue losing equity.
The public is entitled to ask whether percentage commissions protect the industry more effectively than they protect the consumer.
Technology has changed.
Property advertising has changed.
Buyers have changed.
The housing market has changed.
The commission model has barely moved.
If real estate agencies want vendors to keep surrendering $20,000, $30,000 or $40,000 from a single transaction, they should be prepared to demonstrate exactly what that money buys.
The answer cannot simply be:
“That is what we have always charged.”
Source
Commission estimates referenced in this article were produced by interest.co.nz and represent estimated gross residential commission revenue—not net agency profit or individual salesperson earnings.