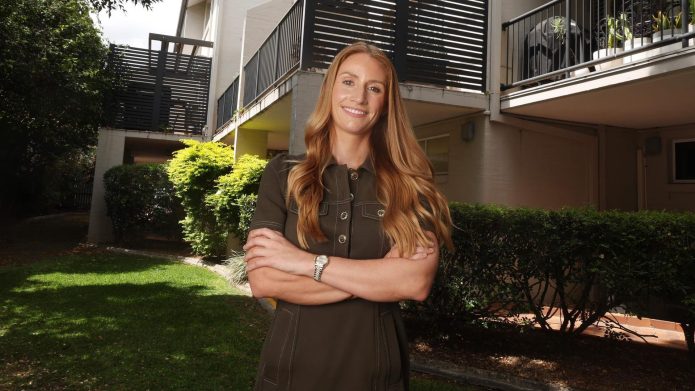
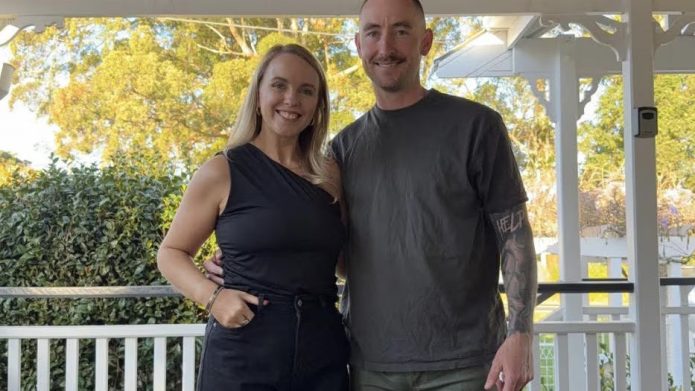

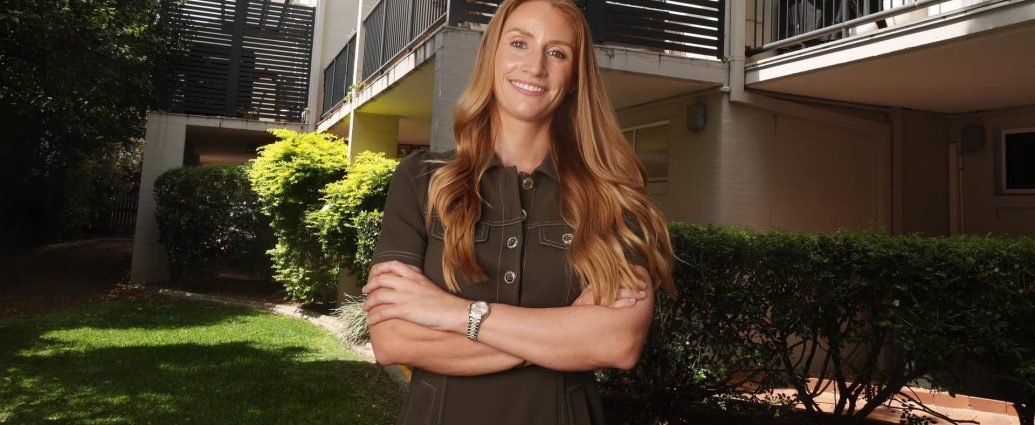
PHOTO: Buyers agent Lauren Jones purchased her first investment property in an Ascot townhouse complex. Picture: Annette Dew
A Brisbane property investor who turned a modest $60,000 salary into a six-property portfolio worth around $5 million has issued a stark warning to young Australians considering the same strategy:
Don’t assume the property investment playbook that worked for her will work for you.
Lauren Jones, 31, built her portfolio after making significant sacrifices to get onto the property ladder, including living cheaply in a five-bedroom share house while saving for her first purchase.
But with major changes to the treatment of negative gearing on established investment properties due from 2027, Jones believes traditional rentvesting — renting where you want to live while owning investment property elsewhere — is about to become considerably more difficult for average-income Australians.
Her message is particularly striking because rentvesting was central to the strategy that helped her build considerable property wealth.
Unlock 1.2 Million+ Aussie Business Contacts — No Subscriptions, No Limits
From a $60,000 salary to a $5 million property portfolio
Jones’ story resembles the investment path promoted to young Australians for much of the past decade.
Rather than waiting until she could afford her ideal owner-occupied property, she entered the market through investment.
She kept her own living costs low, bought property and gradually expanded.
Today, her portfolio consists of six properties valued at approximately $5 million.
But Jones now acknowledges that the conditions that helped make her strategy possible have changed dramatically.
Higher interest rates have already reduced borrowing capacity and increased holding costs.
Changes to negative gearing could alter the equation further.
For somebody earning the same $60,000 salary Jones was earning when she started, she believes replicating her journey would now be substantially harder.

Ms Jones now advises first-time buyers to aim for an owner-occupied home. Picture: Annette Dew
Why negative gearing mattered
One experience in Jones’ own portfolio illustrates the issue.
When interest rates increased, one of her investment properties reportedly ended up running at an annual loss of around $40,000.
Negative gearing provided an important tax offset against that loss.
Without that ability, an investor needs to fund substantially more of the property’s shortfall from their after-tax income.
For an established investor with considerable equity and cash reserves, that may be manageable.
For a 24-year-old trying to build their first investment portfolio, it can be a very different proposition.
That is why Jones argues the changes don’t necessarily eliminate property investment.
Instead, they could change who can afford to be a property investor.
Is rentvesting becoming too risky?
Rentvesting became popular partly because Australia’s most desirable owner-occupier markets became increasingly unaffordable.
The concept was simple.
Rather than stretching to buy a home in Sydney, Melbourne or Brisbane where you actually wanted to live, you could:
Rent in your preferred location.
Buy a more affordable investment property elsewhere.
Use rental income and tax deductions to help hold the property.
Build equity over time.
Eventually use that equity to move further up the property ladder.
Jones believes that model becomes much more difficult when investors lose part of the tax buffer that helped them absorb periods of negative cash flow.
And the problem isn’t occurring in isolation.
Young investors are simultaneously dealing with higher property prices, higher mortgage repayments, tighter serviceability assessments and reduced borrowing capacity.
Remove another part of the financial safety net and the numbers become harder again.
First-home buyers may need to rethink their strategy
Interestingly, Jones’ advice to first-home buyers has now changed.
As a buyer’s agent, she is encouraging many first-time purchasers to focus on buying an owner-occupied home rather than immediately pursuing the rentvesting strategy she herself used.
That represents a significant shift.
For years, aspiring buyers who couldn’t afford their desired home were frequently told to “rent where you want to live and invest where you can afford.”
For some buyers, that may still work.
But the financial assumptions underpinning that strategy need to be reconsidered if the tax treatment of established investment properties changes.
The wealthy can still play the property game
There is another side to Jones’ warning — and arguably it’s the most interesting.
She isn’t leaving property investment.
She’s changing strategy.
Jones has reportedly invested around $500,000 cash into developing a five-bedroom rooming house in Kallangur, north of Brisbane.
The project is expected to generate around $120,000 in annual rental income, with Jones targeting approximately a 10% yield.
Because it involves new housing supply, the project can also retain eligible depreciation benefits available to new construction.
It is exactly the sort of investment Jones believes policymakers should want to encourage: private capital creating additional accommodation.
Australia’s property investment market could split in two
The Kallangur development also exposes a potential unintended consequence of Australia’s changing property investment landscape.
Sophisticated investors with substantial equity or cash can pivot.
They can build.
They can develop.
They can buy higher-yielding assets.
They can pursue rooming houses or other specialist accommodation.
They can restructure debt.
And importantly, they can withstand periods of negative cash flow.
A young investor earning $60,000 or $70,000 generally cannot.
That potentially creates a two-tier investment market.
At one end are established investors with capital.
At the other are aspiring investors trying to purchase their first or second property.
The reforms may affect those two groups very differently.
Could the reforms actually favour wealthy investors?
That’s the central contradiction raised by Jones.
Policies designed partly to reduce the advantages enjoyed by property investors could ultimately make capital more important.
If an investment strategy requires larger deposits, stronger cash flow and greater reserves, wealthy investors are naturally better positioned to participate.
Jones argues that removing negative gearing from established properties won’t necessarily prevent wealthy Australians from buying property.
They may simply change what they buy.
The person who could be squeezed out is the ordinary wage earner trying to acquire their first investment property.
What happens to established homes?
There is also a broader housing-market question.
If the tax system increasingly encourages investors towards new construction, demand for newly built investment properties could increase.
That may encourage additional housing supply — one of the intended outcomes.
But established investment properties don’t disappear.
They still need buyers.
If investor demand for established properties falls, owner-occupiers and first-home buyers may have less competition for those homes.
That would be a positive outcome for buyers.
The unanswered question is whether the shift in investor behaviour ultimately produces enough new housing supply to compensate for any reduction in private landlords purchasing existing rental properties.
That will take time to become clear.
Rentvesting isn’t necessarily dead — but the maths is changing
Calling rentvesting “dead” makes a powerful headline.
The reality is more nuanced.
Rentvesting will remain viable for some Australians.
A strongly yielding investment property purchased at the right price with manageable debt could still make financial sense.
But the strategy becomes considerably less forgiving when borrowing costs are high and tax advantages are reduced.
Investors may consequently place much greater emphasis on cash flow, rental yield and the ability to survive higher interest rates, rather than relying primarily on capital growth.
And that may represent the biggest change of all.
Australia’s property investment boom encouraged a generation to believe that getting into the market was the most important thing.
The next generation may have to be far more selective about what they buy, how much debt they take on and whether they can afford to hold the property when things go wrong.
The warning for Australia’s next generation of property investors
Jones’ own experience gives her argument considerable weight.
She built substantial property wealth using a strategy available to ordinary wage earners willing to sacrifice and take calculated risks.
Now, with a $5 million portfolio behind her, she believes the ladder she climbed is becoming harder for others to access.
Her own next move demonstrates the difference.
She has enough capital to adapt.
Many first-home buyers and aspiring investors don’t.
And that may ultimately prove to be one of the biggest consequences of Australia’s changing property tax landscape.
The wealthy may continue investing in property.
The question is whether ordinary Australians will still be able to follow them.
SOURCE: NEWS.COM.AU